Benchmark your growth strategy against the market
Global ad spend grew 14.77% QoQ after falling 8.79% in Q1. Advertisers increased budgets across almost every region and vertical, with Android and iOS spend rising at nearly identical rates.
Inventory followed a different pattern. Android impressions grew 6.40%, while iOS impressions fell 5.40%. The tighter supply pushed iOS CPM up 21.36%, almost three times the increase on Android. Global CPI rose 8.47%, even though IPM improved for the second consecutive quarter.
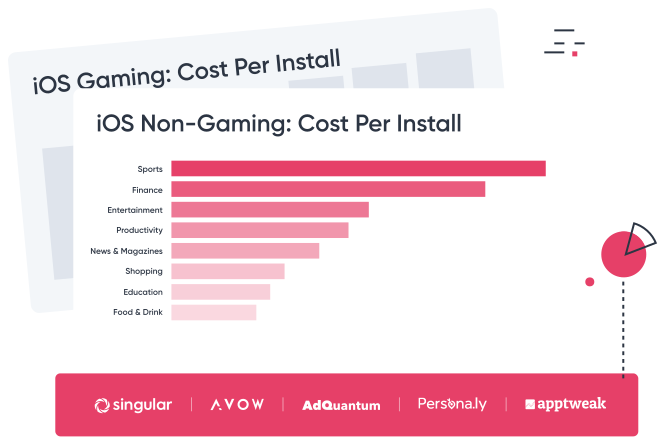
The Q3 2026 Quarterly Trends Report explains how these market changes affected acquisition costs across platforms, regions, verticals, and gaming genres.
If you are allocating budget across platforms, markets, or verticals, the report will help you:
► Why iOS got so much more expensive than Android last quarter
► How to tell if your CPI increase was market rate or something you can fix
► The real iOS premium for your vertical, from 1.5x all the way to 12.4x
► The three verticals that got cheaper to enter, while everything else went up
► Where revenue lands by platform, and the two verticals where Android takes the majority
► Top networks with the most spend and advertisers, plus the first AI platform as an entrant
► ATT opt-in by vertical, and where the budget sits versus where the signal sits
► CPI, CPM, CTR, CVR, and IPM benchmarks for every country tier and vertical
Billions of dollars of spend
Trillions of impressions
Billions of installs